
HomeMember stories
Real member stories. Every number adds up.
From first-time buyers to business owners.
All stories
AllReal member stories. Go through them one by one, or pick one below.
-
EthanSalaried worker Extra each month, after instalmentsRM3,000
Two Firesales properties, one bought 26.56% below market valueHe was ready to carry a 30-year loan on a home to live in.
Instead, he invested first. The two properties bring in RM8,000 a month in rent, one with a rental yield of 11.04%. The extra RM3,000 a month is after instalments and other costs.
-
Jeffery TeoBusiness owner, East Malaysia For justRM434,000
he won a shop with a market value of RM2,039,400 at auctionDuring the MCO, his business ran out of cash and the bank turned down his loan.
With guidance from CY Academy, he restructured his financing and got through it, then bought this shop at auction.
-
Mr LooAge 28 · earns RM6,000 a month Extra each month, both homes togetherRM2,050
Home 1: RM885. Home 2: RM1,165.He bought the first in his own name. Within a year, his wife bought the second.
Both were bought below market value, and after the instalment, each one leaves money over every month.
Home 1In his name Home 2Within a year, in his wife’s name · age 26 · earns RM5,000 a month Bought at RM400,000 RM360,000 Market RM600,000RM460,000Rent RM3,218 RM3,140 Instalment RM2,333 RM1,975 Left over RM885 RM1,165 -
Wee PinAge 26 · Airbnb host Extra each monthRM912
after the rent pays the instalmentHe started with Firesales: the rent covers the instalment, with some left over.
He bought it RM145,000 below market value.
Bought at RM335,000 Market RM480,000Rent RM3,000 Instalment RM2,088 Left over RM912 -
EuniceBorn 1995 or later Extra each month, after instalmentsRM1,000+
A first-timer, using bank financing to buy and renovateShe thought doing her own homework and finding a property agent would be enough. Instead, screening properties and sorting out the loan took a lot of time, and she nearly fell into a trap.
The team helped her shortlist high-rent properties and get the right loan package.
-
Positive cash flow each month
RM1,109
Net rent RM3,400 minus the RM2,291 instalmentAge 38, buying his first property with CY, looking for passive income.
A unit in Bangsar South, set up as 5 rooms to rent. Market value RM580,000, bought at a Firesales price of RM425,000, which is 26.7% below market value. Net rental yield about 9.6%.
Market RM580,000Bought at RM425,000 Below market 26.7% Net rent RM3,400 Instalment RM2,291 Net yield 9.6% Left over RM1,109 Net rent: total rent minus about RM450 a month in costs and a 15% management fee. Yield is based on the purchase price.
-
Positive cash flow each month
RM1,472
Net rent RM3,510 minus the RM2,038 instalmentAge 28, a budget of about RM400k, freehold only.
A unit in Sentul, set up as 5 rooms to rent. Market value RM500,000, bought at a Firesales price of RM405,000, which is 19.0% below market value. Net rental yield about 10.4%.
Market RM500,000Bought at RM405,000 Below market 19.0% Net rent RM3,510 Instalment RM2,038 Net yield 10.4% Left over RM1,472 Net rent: total rent minus about RM450 a month in costs and a 15% management fee. Yield is based on the purchase price.
-
Positive cash flow each month
RM1,164
Net rent RM3,315 minus the RM2,151 instalmentAge 38, buying his second property, looking for passive income.
A unit in Petaling Jaya, set up as 5 rooms to rent. Market value RM480,000, bought at a Firesales price of RM410,000, which is 14.6% below market value. Net rental yield about 9.7%.
Market RM480,000Bought at RM410,000 Below market 14.6% Net rent RM3,315 Instalment RM2,151 Net yield 9.7% Left over RM1,164 Net rent: total rent minus about RM450 a month in costs and a 15% management fee. Yield is based on the purchase price.
-
Positive cash flow each month
RM1,127
Net rent RM3,850 minus the RM2,723 instalmentAge 31, a budget of about RM500k, looking for higher cash flow.
A 3+1 bedroom unit in Bukit Jalil, set up as 6 rooms to rent. Market value RM650,000, bought at a Firesales price of RM520,000, which is 20.0% below market value. Net rental yield about 8.9%.
Market RM650,000Bought at RM520,000 Below market 20.0% Net rent RM3,850 Instalment RM2,723 Net yield 8.9% Left over RM1,127 Net rent: total rent minus about RM450 a month in costs and a 15% management fee. Yield is based on the purchase price.
-
Positive cash flow each month
RM434
Net rent RM3,536 minus the RM3,102 instalmentAge 35. He first meant to live in it, then rented it out so the rent pays the loan.
A unit in Subang Jaya, set up as 5 rooms to rent. Market value RM800,000, bought at a Firesales price of RM600,000, which is 25.0% below market value. Net rental yield about 7.1%.
Market RM800,000Bought at RM600,000 Below market 25.0% Net rent RM3,536 Instalment RM3,102 Net yield 7.1% Left over RM434 Net rent: total rent minus about RM450 a month in costs and a 15% management fee. Yield is based on the purchase price.
-
≈ RM2,000
Cash flow a month, after the rent pays the instalmentA salary of just over RM4,000, and the very first property bought at a Firesales price.
A property the bank valued at RM400k, sold for RM320k by an owner who needed to sell fast, 20% below valuation. It’s within walking distance of a mall, a hospital and offices, with the LRT nearby. Rented out, it brings in about RM3,800 a month against an instalment of about RM1,800, leaving about RM2,000 extra every month.
-
3.98%7.78%
Rental yield, on the same RM2,800 rentThe first owner paid too much. A member won it at auction for half the price.
A unit near TRX in Kuala Lumpur. The first owner bought it new for RM843,600, but the RM2,800 rent couldn’t cover the loan, and the bank put it up for auction. A member won it for RM432,000 and rents it out for the same RM2,800.
-
RM500kRM430k
Market value, then the Firesales price paidAge 29, a first property, limited funds, and it had to earn from day one.
Ian is on the CY team. The property is in PJ, within walking distance of office towers and close to the LRT and a university, so there’s a wide pool of tenants. Market value RM500k, bought at a Firesales price of RM430k. Total rent is now about RM3,920 a month, a gross rental yield of about 10.9% on the purchase price.
-
RM38,331RM14,826
Monthly repaymentsCredit card debt cleared, and able to apply for a RM1.1M home loan again.
A father paying for his daughter’s studies in the UK had run up over RM300,000 in credit card debt. His income was RM28,000, yet he had to repay RM38,331 every month. After restructuring, the same bank that had turned him down approved a new plan.
-
11.5%
Rental yieldBought more than 20% below valuation, with about RM1,500 extra a month.
A serviced apartment near a mall and the LRT, opposite an office park of multinational companies, with a university shuttle bus. Bank valuation RM460k, bought for RM355k. Set up as a Dual Key, two units rented out separately: about RM3,400 a month in rent after WiFi, and about RM1,500 left every month after the instalment.
-
17.5%and21.1%
below bank valuationMaximum bid set first, and no chasing past it. Both are rented out.
Before every auction, Alex works out the maximum bid with the method from class. Both Lelong properties were bought below bank valuation, and both are now rented out.
-
RM1.5MRM1.33M
Market value, then the price after negotiationHis first shop, after buying several homes through Firesales.
A freehold 3-storey shop with a market value of about RM1.5M. CY negotiated the price down to RM1.33M for him. A 30-year loan, with the legal fees financed too, at about RM6,680 a month. The rent was RM7,300 a month and has gone up to RM7,400 since handover: a rental yield of about 6.7%, with positive cash flow every month.
-
RM315kRM470k
Won at the reserve price, sold 11 months laterAt a first Lelong, the maximum bid was set and kept.
A first Lelong at 26: the property was won at the reserve price of RM315k and sold 11 months later for RM470k. Other costs came to about RM31.5k, for a profit of about RM123.5k before tax.


Members’ own experiences. Results vary from person to person and do not indicate future returns. Property investment carries risk.
Want to run the numbers yourself?3 nights in a row on Zoom, held in Mandarin: find property below market value and work out the cash flow first.
Join Lelong 致富学 freeTakes a minute. Zoom link by WhatsApp and emailWe buy the way we teach.
Same method, our own properties.
From Chris to the team, everyone uses the same method to buy their own rental properties, one at a time, taking every step themselves.
We’ve walked this road ourselves. You can start on it too, from step one.
Start with the free class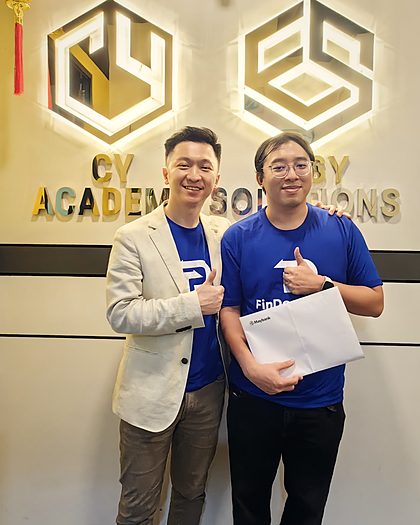
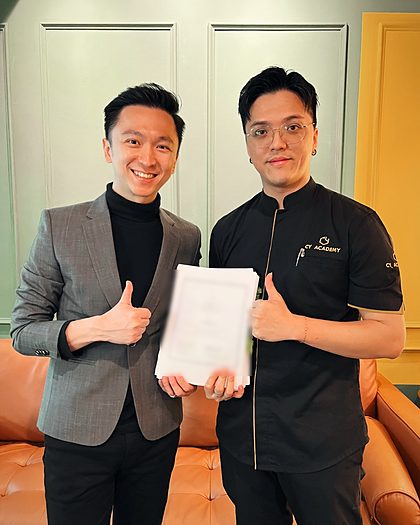


Team members signing their own sale and purchase agreements and loan documents, one after another. You could be next
Get the numbers right,
then buy right.
The rule behind every story on this page.
Every member here started in the same place: a free online class, learning to work out the cash flow first.